Executive member benefit
Honest guidance on what affects your credit standing and the concrete steps that improve it. Guidance, not a repair service, and no empty promises.
Let us be direct: this benefit is guidance, not a credit repair service. The chamber does not dispute items on your behalf, does not promise score changes, and does not sell credit repair. Anyone who promises to erase accurate negative information or guarantees a fast score jump is not being straight with you, and we will not be that voice.
What the chamber does provide is a clear, plain-language explanation of your credit picture and a step-by-step improvement plan you can work yourself. You will understand what lenders see when they pull your file, which factors are helping you, which are hurting you, and what to do about each one, in what order.
Credit takes consistent behavior over time to build. There are no shortcuts in this guidance, only the real steps, explained so you can actually follow them.
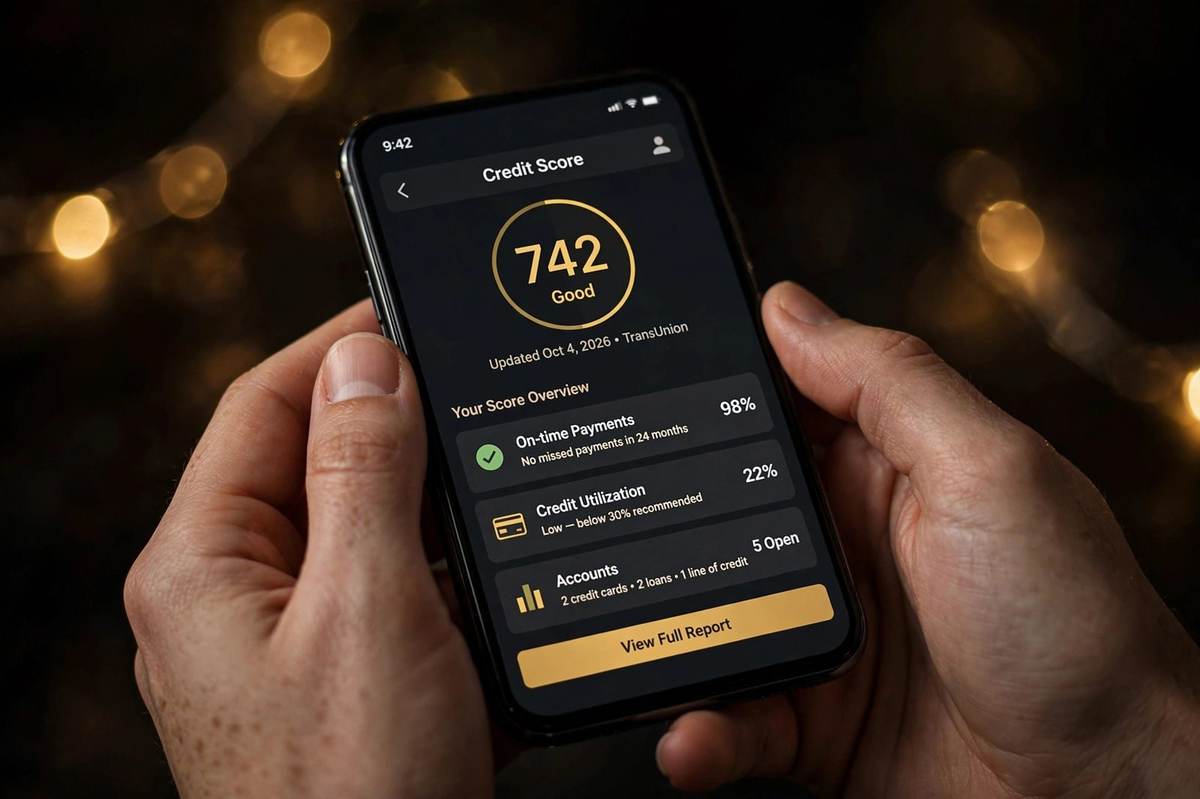
Lenders look at patterns, not single moments. These are the patterns that shape what they see.
Whether you pay vendors, lenders, and creditors on time, every time. Late or missed payments are the heaviest weight on a credit file, for businesses and owners alike.
How much of your available credit you are using. Balances that sit near the limit signal strain, even when payments are current. Lower balances relative to limits read as stability.
How long your accounts have been open and how varied they are. A longer, steady history gives lenders more evidence of reliability than a brand-new file.
Liens, judgments, and collections attached to the business or the owner. These carry serious weight, and resolving or addressing them is usually a priority step.
For small businesses, lenders almost always look at the owner's personal file too. Your personal payment history and utilization directly affect what your business can access.
Mistakes happen on credit reports more often than people expect: wrong balances, accounts that are not yours, old items that should have aged off. Finding them is step one.
No shortcuts, just the real moves, explained so you can follow them yourself.
Open a business bank account and use a business card only for business spending. Clean separation makes your business legible and protects your personal file.
Set up autopay where you can and calendar reminders where you cannot. Consistent on-time payments are the single most important habit in credit.
Review your personal reports from the major bureaus and check your business credit reports too. You have the right to dispute inaccurate information directly, for free.
Beyond those three foundations: keep balances low relative to your limits rather than maxing cards out, avoid opening many new accounts at once, and address collections or past-due items with a plan instead of ignoring them. If something on a report is wrong, dispute it in writing with the bureau and keep copies of everything you send.
A word of caution: be skeptical of any company that demands large upfront fees or promises specific score increases. You can do the core work yourself, and this guidance shows you how.
You leave with a plain-language explanation of your credit picture: what lenders see, what is helping, and what is hurting. Alongside it, a step-by-step improvement plan ordered by impact, so you know what to do this month, what to do next quarter, and what to keep doing as a habit.
This is slow, honest work, and it is some of the highest-leverage work an owner can do. Every on-time payment and every error corrected is a brick in the foundation your business will borrow against later.
Credit repair readiness guidance is part of every executive membership. Prefer to start free? Join the community and learn alongside fellow owners.